Laopu Gold Performance Warning: 'Sell' Signal Amid Gold Price Decline and Growth Bottleneck
Keywords
Laopu Gold; Performance Warning; Gold Price Decline; China Merchants Securities; Sell Rating
Introduction
On July 28, 2026, China Merchants Securities International issued a strong warning signal for Laopu Gold (stock code: XXXX.HK). The report shows that the company's Q2 2026 performance is expected to be far worse than Q1 and about 10% below the already lowered market expectations. Meanwhile, international spot gold prices have fallen more than 20% from their highs, coupled with slowdown in both online and offline channels. Laopu Gold faces multiple pressures. China Merchants Securities slashed its target price from HKD 730 to HKD 304, directly downgrading the rating from 'Hold' or 'Buy' to 'Sell'. This rating change rattles the market, reflecting the severe environment for the gold jewellery industry caught between high base effects, gold price volatility, and weak demand.
Performance Warning: Q2 Significantly Below Expectations
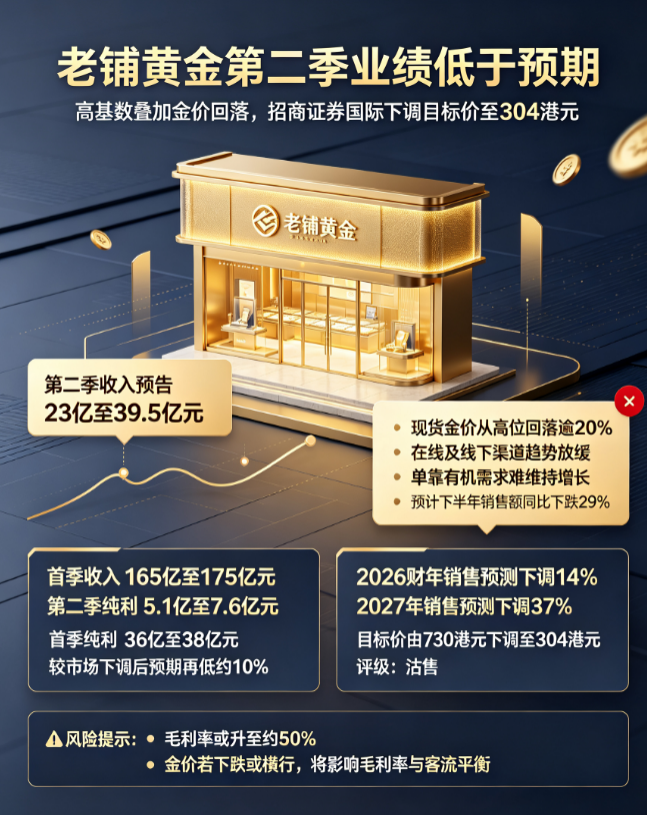
According to the report by China Merchants Securities International, Laopu Gold expects Q2 2026 revenue to range from RMB 2.3 billion to RMB 3.95 billion, a sharp decline compared to Q1's RMB 16.5 billion to 17.5 billion. More critically, Q2 net profit is estimated at only RMB 510 million to 760 million, far below Q1's RMB 3.6 billion to 3.8 billion. Even considering seasonal fluctuations, such a drastic sequential decline shocks the market.
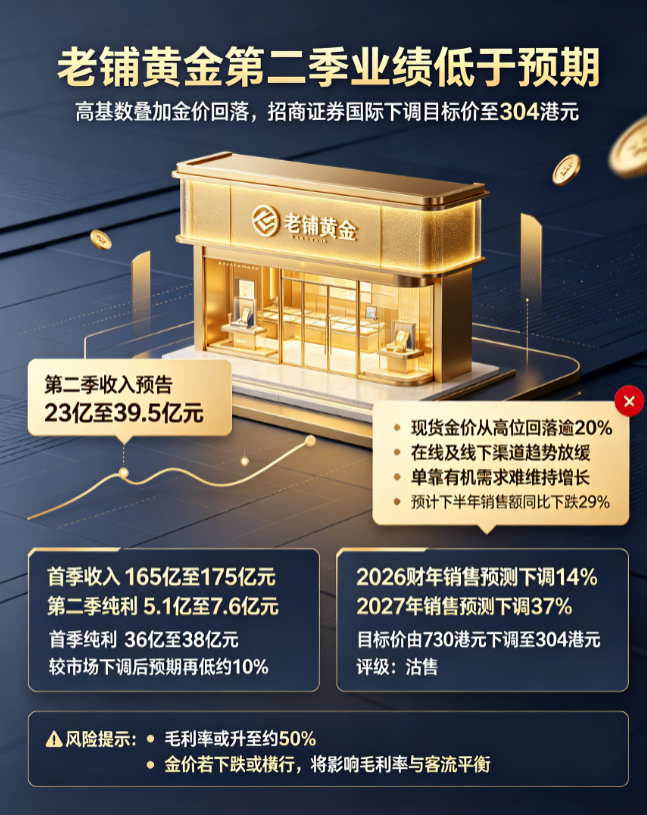
The chart compares Laopu Gold's Q1 and Q2 2026 key financial data, clearly showing the sharp decline in revenue and net profit.
China Merchants Securities pointed out that the company's Q2 performance was about 10% lower than the already lowered market expectations, meaning analysts' previously conservative forecasts were still too optimistic. This performance 'stall' is not an isolated incident but a microcosm of the overall cooling of the gold jewellery industry. During the sharp gold price rally in 2025 driven by high inflation and safe-haven demand, Laopu Gold achieved explosive growth due to brand premium and product innovation. However, as gold prices fell from highs, the pre-loaded consumer demand quickly receded, and the company faced a double blow of 'expectation gap' and 'fundamental weakness'.
Gold Price High Decline and Growth Dilemma
International spot gold prices have fallen more than 20% from their 2026 high of about USD 5,300 per ounce to about USD 4,100 per ounce currently. The decline directly suppresses consumer willingness to buy – gold jewellery has both consumption and investment attributes. When gold prices rise, 'buy on uptrend' psychology drives hoarding demand; when prices fall, consumers wait and see, curbing immediate consumption. China Merchants Securities noted that Laopu Gold's online and offline channel trends are both slowing, and organic demand alone cannot sustain the previous growth trajectory.
More worryingly is the high base effect. In H2 2025, driven by Fed rate cut expectations and geopolitical risks, gold prices continued to climb, and Laopu Gold's sales in the same period hit historic highs. Entering H2 2026, this high base will put immense pressure on year-over-year growth. China Merchants Securities expects the company's H2 2026 sales to decline 29% year-over-year. This means even if the company stabilizes sequentially in H2, year-over-year data will remain bleak.
Double-Edged Sword of Gross Margin and Dilemma
Despite overall performance pressure, Laopu Gold's Q2 gross margin may improve. The report noted that thanks to earlier high-price increases (passing on earlier gold cost to consumers) and low-cost replenishment (purchasing raw materials at lower costs after gold price decline), Q2 gross margin may rise to about 50%. This seems like a positive sign, but it hides deeper financial concerns.
China Merchants Securities analyzed that if gold prices continue to decline or remain sideways for a long time, Laopu Gold will face a typical dilemma: either maintain the current higher gross margin and stick to pricing strategy, but this may lead to further loss of store traffic as consumers shift to more cost-effective competitors; or proactively cut prices to attract traffic, but this would directly squeeze profit margins, causing gross margin to fall from 50%. Whichever path it takes, the company will struggle to find a balance between 'protecting profit' and 'protecting traffic'. This structural contradiction is the main reason for China Merchants Securities' sharp target price reduction.
Future Outlook and Investment Advice
Based on the above judgment, China Merchants Securities International has lowered its sales forecasts for Laopu Gold for FY2026 and FY2027 by 14% and 37% respectively, while raising gross margin forecasts by 5.5 and 6 percentage points. On the surface, gross margin increase seems to indicate improved profitability, but the reduction in sales revenue far exceeds the gross margin increase, leading to a significant deterioration in overall net profit expectations. The final target price was slashed from HKD 730 to HKD 304, a drop of over 58%, with a clear 'Sell' rating.
From an industry perspective, Laopu Gold's predicament is not unique. China's gold jewellery consumption experienced 'compensatory growth' in 2025, entering a rational return period in 2026. Gold price volatility exacerbates the unpredictability of consumption pace, and the tug-of-war between price hikes and volume maintenance among brands will run through the entire adjustment cycle. For investors, the current phase should focus on gold jewellery companies' inventory management ability, channel structure flexibility, and effectiveness of gold hedging strategies. The problem Laopu Gold exposes is whether, when growth engine switches from 'rising gold price + strong consumption' to 'falling gold price + weak consumption', the company has sufficient anti-cyclical resilience. At least from China Merchants Securities' report, the answer is not optimistic.
Conclusion
Laopu Gold's performance warning is a mirror reflecting the vulnerability of the gold jewellery industry at a cyclical turning point. The triple factors of gold price decline from highs, high base effect, and slowing consumer demand have pushed the company from rapid growth into a downward path. China Merchants Securities' 'Sell' rating is not alarmist, but a prudent judgment based on financial data and industry logic. For investors, be wary of potential chain reactions from continued gold price decline – including inventory impairment risk, channel contraction pressure, and brand premium dilution. While gold's 'shine' temporarily dims, waiting for market clearing and fundamental stabilization may be a more rational choice.